
Purchasing property represents one of the most significant financial decisions most Australians will make. The journey of buying homes involves careful planning, strategic decision-making, and thorough research to ensure you secure the right property at the right price. Whether you're a first-time buyer entering the market or an experienced investor expanding your portfolio, understanding the complete process from initial research through to settlement helps you navigate this complex transaction with confidence and clarity.
Understanding Your Financial Position Before Buying Homes
Before you begin inspecting properties, establishing a clear picture of your financial capacity forms the foundation of successful property purchasing. This assessment goes far beyond simply knowing your savings balance-it requires a comprehensive understanding of your borrowing power, ongoing commitments, and long-term financial goals.
Calculating Your Genuine Borrowing Capacity
Most buyers overestimate or underestimate what they can genuinely afford. Your borrowing capacity depends on multiple factors including your income, existing debts, living expenses, and credit history. Lenders typically assess your financial position by examining:
- Gross annual income from employment, business, or investments
- Existing financial commitments including personal loans, credit cards, and other debts
- Monthly living expenses based on your actual spending patterns
- Credit score and history which influences interest rates and approval likelihood
- Deposit size and source including savings, gifts, or equity from existing properties
Financial institutions now apply stringent serviceability tests that factor in potential interest rate rises. Understanding how to prepare financially ensures you enter the market with realistic expectations and avoid the disappointment of failed loan applications after finding your ideal home.
Building Your Deposit and Understanding Additional Costs
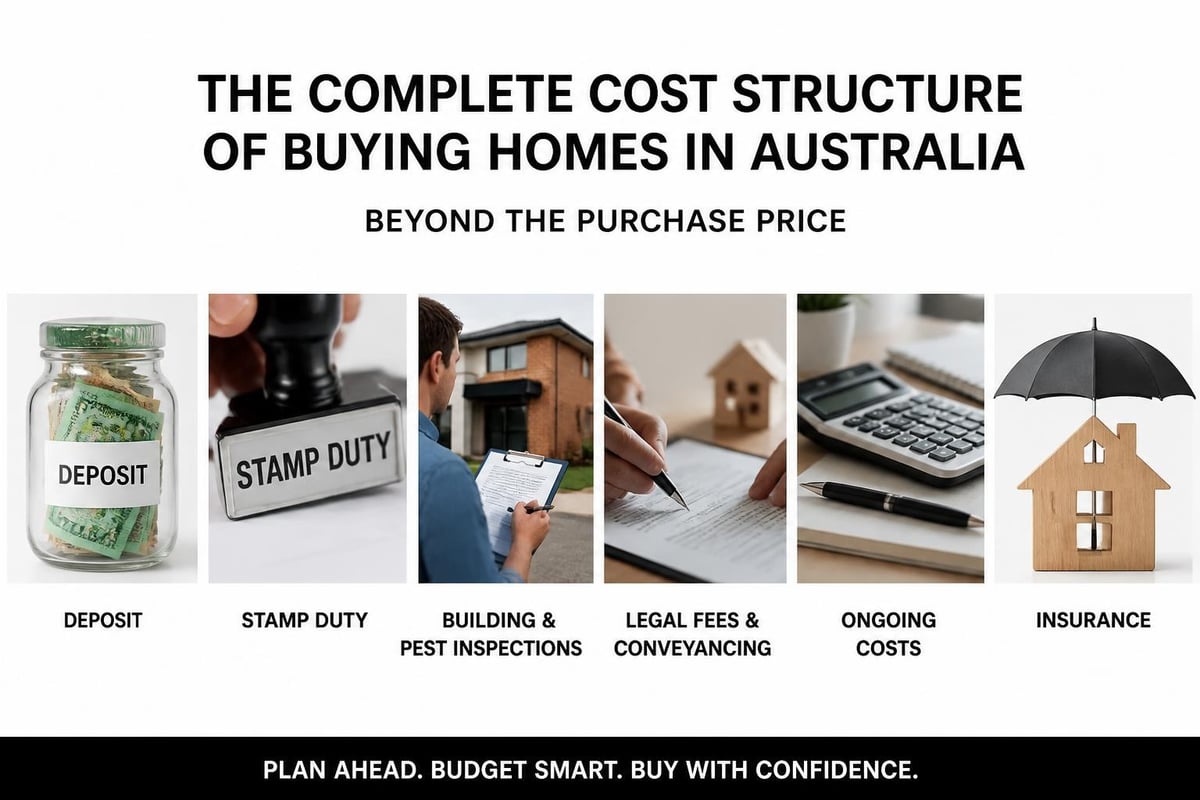
The deposit represents just one component of the upfront costs involved in buying homes. Most lenders require a minimum 20% deposit to avoid lenders mortgage insurance, though some first-home buyer schemes allow smaller deposits with government guarantees.
Budget for these additional expenses beyond your deposit:
| Cost Category | Typical Range | Notes |
|---|---|---|
| Stamp Duty | 3-5% of purchase price | Varies by state; exemptions may apply for first-home buyers |
| Building & Pest Inspections | $400-$800 | Essential for informed purchasing decisions |
| Conveyancing/Legal Fees | $1,500-$3,000 | Professional guidance through settlement |
| Loan Application Fees | $0-$1,000 | Some lenders waive these fees |
| Moving Costs | $500-$2,000 | Transport, connections, and immediate maintenance |
Defining Your Property Requirements and Location Priorities
Successful property purchasing begins with clarity about your genuine needs versus aspirational wants. Creating a prioritised list of requirements helps focus your search and prevents emotional decision-making when viewing properties.
Essential Versus Desirable Features
Distinguish between non-negotiable requirements and features you'd prefer but could compromise on. Your essential list might include proximity to work, number of bedrooms, or accessibility features, while desirable features could be a second bathroom, outdoor entertaining area, or garage space.
Consider how your needs might evolve over the next 5-10 years. Families may require space for growing children, while professionals might prioritise home office potential in an increasingly flexible work environment.
Researching Suburbs and Local Markets
Location fundamentally determines both lifestyle satisfaction and long-term capital growth. When buying homes in Sydney's south-west corridor, suburbs like Padstow, Revesby, and Panania offer distinct advantages including established infrastructure, diverse housing stock, and strong community networks.
Research these location factors thoroughly:
- Transport connectivity and commute times to employment centres
- School zones and educational facilities for families
- Local amenities including shopping centres, healthcare, and recreational facilities
- Future development plans that might enhance or detract from the area
- Historical price trends and suburb growth patterns
- Community demographics and neighbourhood character
Spending time in potential suburbs at different times throughout the week provides invaluable insights that online research cannot replicate. Visit local cafes, observe street activity, and speak with residents to gain authentic perspectives on daily life in the area.
Engaging Professional Support for Confident Decision-Making
The complexity of buying homes makes professional guidance invaluable. Assembling the right team of experts protects your interests and helps navigate potential obstacles throughout the purchasing journey.
Working With a Knowledgeable Real Estate Agent
Engaging an experienced buyer's agent or working closely with a trusted local agent provides access to market intelligence, property insights, and negotiation expertise. When working with Steven Cirillo, buyers benefit from Buyer & First Home Buyer Guidance that helps navigate the entire purchasing journey with confidence. His extensive local expertise across Revesby, Padstow, Panania, and surrounding suburbs ensures buyers receive valuable advice that helps them secure the right property at the right price.
A skilled agent understands current market conditions, identifies properties before they're widely advertised, and provides honest assessments of property value and potential issues. They can also guide you through the often-stressful important steps when buying a home that many first-time buyers find overwhelming.
Securing Mortgage Pre-Approval
Obtaining pre-approval before actively house hunting provides several strategic advantages. It confirms your borrowing capacity, demonstrates serious intent to vendors, and accelerates the purchasing process when you find the right property.
Pre-approval involves submitting comprehensive financial documentation to your chosen lender, who then issues conditional approval for a specific loan amount. This conditional approval typically remains valid for 90 days and allows you to make offers with confidence.
Conducting Thorough Property Inspections and Due Diligence
Never underestimate the importance of comprehensive property inspections when buying homes. What appears perfect during a brief viewing may conceal significant structural, pest, or compliance issues that become expensive problems after settlement.
Professional Building and Pest Inspections
Engaging qualified building inspectors and pest specialists represents money well spent. These professionals identify issues invisible to untrained eyes, including structural defects, water damage, termite activity, and non-compliant modifications.
A detailed inspection report provides:
- Comprehensive assessment of the building's structural integrity
- Identification of major and minor defects requiring attention or repair
- Pest activity evidence including termites, borers, and fungal decay
- Cost estimates for remedial work on identified issues
- Negotiation leverage to adjust your offer price or request repairs before settlement
Understanding how home appraisals work also helps you appreciate the professional assessment process that lenders require before approving your mortgage.
Reviewing Property Documentation and Contracts
Legal documents associated with property purchases contain crucial information that affects your ownership rights and future obligations. Your conveyancer or solicitor should review all contracts thoroughly before you sign anything.
Key documents requiring careful examination include:
- Contract of sale with all special conditions clearly stated
- Section 32 vendor's statement (in Victoria) or equivalent disclosure documents
- Title searches confirming legal ownership and any encumbrances
- Planning certificates showing zoning and development restrictions
- Strata reports for apartments or townhouses detailing body corporate finances and issues
Making Strategic Offers and Negotiating Effectively
Once you've identified a suitable property and completed due diligence, the negotiation phase determines whether you secure the home at a fair price. Effective negotiation requires market knowledge, emotional control, and strategic thinking.
Understanding Current Market Conditions
Property markets fluctuate between buyer's markets, where supply exceeds demand, and seller's markets, where competition drives prices upward. Recognising current market dynamics in your target suburb influences your negotiation approach.
In balanced or buyer's markets, you hold greater negotiating power and can make lower initial offers. During competitive seller's markets, you may need to present strong offers quickly to avoid missing opportunities. Research recent comparable sales to understand realistic price expectations for your desired property type.
Structuring Your Offer Strategically
Your initial offer communicates serious intent while leaving room for negotiation. Consider these strategic elements when making offers on homes:
| Offer Component | Strategic Consideration |
|---|---|
| Price | Based on comparable sales, property condition, and market conditions |
| Settlement Period | Longer settlements suit vendors with moving challenges; shorter suits investment buyers |
| Subject to Finance Clause | Protects you if loan approval fails; vendors prefer unconditional offers |
| Building Inspection Clause | Allows withdrawal if significant defects discovered |
| Cooling-off Period | Provides time for final consideration (varies by state) |
Avoid revealing your maximum budget or displaying excessive emotional attachment during negotiations. Successful buyers remain composed, reference objective market data, and know when to walk away from properties that don't represent fair value.
Navigating Different Purchasing Methods
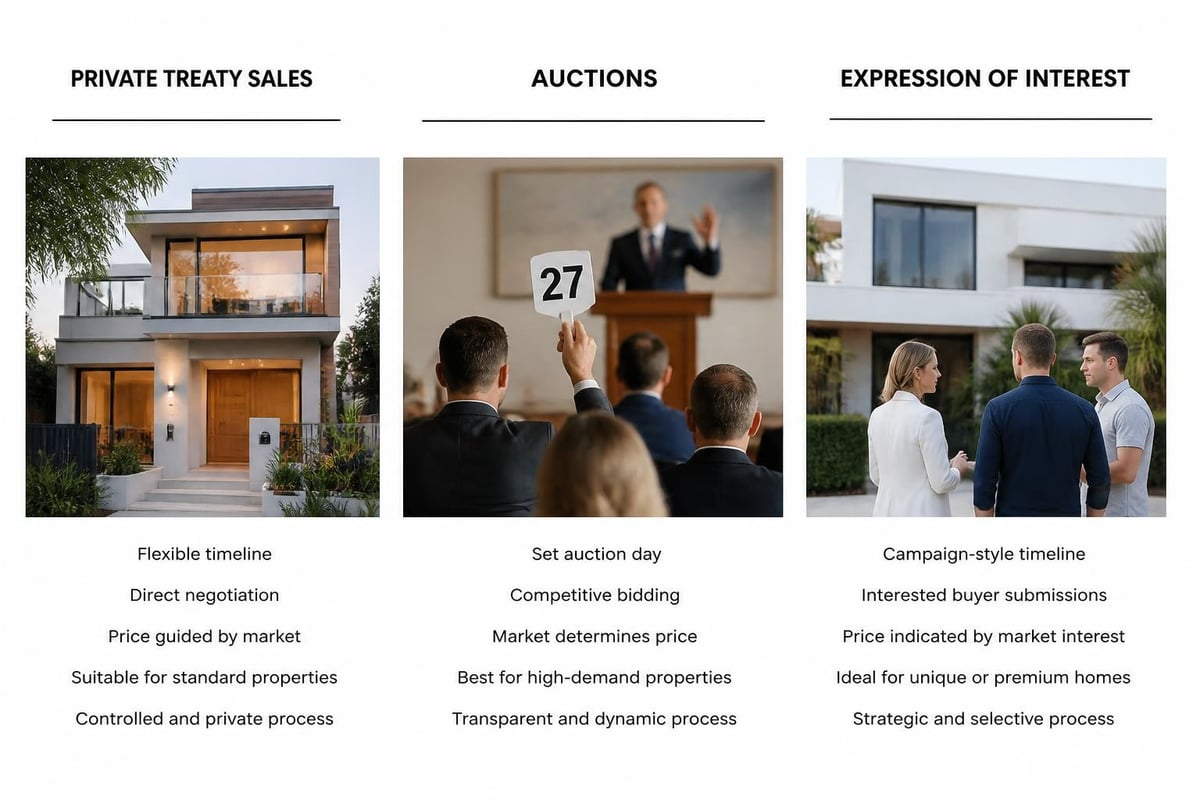
Australian property markets utilise various sale methods, each requiring different approaches and strategies. Understanding these methods helps you prepare appropriately and maximise your chances of successful purchase.
Private Treaty Sales
Private treaty represents the most common sale method where the vendor sets an asking price and negotiates directly with interested buyers. This method allows time for due diligence, thoughtful consideration, and back-and-forth negotiation until both parties reach agreement.
The private treaty process typically unfolds as follows:
- Property advertised with guide price or price range
- Interested buyers inspect and conduct due diligence
- Buyers submit written offers to the agent
- Agent presents offers to vendor who may accept, reject, or counter
- Negotiation continues until agreement reached or buyer withdraws
- Contracts exchanged and cooling-off period commences
Auction Campaigns
Auctions create competitive tension that can drive prices beyond initial expectations. Properties selling via auction require unconditional bids, meaning you must complete all inspections and finance approval before auction day.
Successful auction participation requires:
- Thorough pre-auction preparation including finance approval and property inspections
- Clear maximum bid limit determined by property value and your budget
- Strategic bidding approach that projects confidence without revealing your limit
- Emotional discipline to avoid getting caught in competitive bidding beyond your limit
- Backup plan if bidding exceeds your maximum acceptable price
Many buyers find auctions stressful and prefer avoiding this sale method entirely. However, some of the best properties sell via auction, making it essential to understand this process when buying homes in competitive markets.
Managing the Settlement Process and Final Steps
After your offer is accepted, several weeks of administrative processes occur before you receive the keys to your new home. Understanding settlement procedures prevents last-minute surprises and ensures a smooth transition to ownership.
Contract Exchange and Cooling-Off Period
Following offer acceptance, contracts are formally exchanged between buyer and vendor. In most states, buyers receive a cooling-off period (typically 3-5 business days) allowing contract withdrawal with minimal penalty. This period provides final opportunity to reconsider or address any concerns.
During this period, ensure your finance approval remains current, review all contract conditions carefully, and maintain open communication with your conveyancer regarding progress toward settlement.
Pre-Settlement Inspections and Final Checks
Most contracts allow a final inspection within days of settlement. This inspection confirms the property remains in substantially the same condition as when you made your offer, all agreed repairs have been completed, and items included in the sale remain present.
Check these elements during your final inspection:
- Property condition matches original inspection
- All fixtures and fittings listed in contract are present
- Agreed repairs completed to satisfactory standard
- No new damage has occurred
- Gardens and outdoor areas maintained
- All keys, remotes, and access codes available
Settlement Day and Taking Possession
Settlement occurs when legal ownership transfers from vendor to buyer. Your conveyancer coordinates with the vendor's representative, your lender, and various government departments to complete all necessary documentation and financial transfers.
On settlement day, several transactions occur simultaneously:
- Your lender releases loan funds to your conveyancer
- Your conveyancer transfers purchase price to vendor's representative
- Title transfers into your name at the relevant land titles office
- Any existing mortgages on the property are discharged
- Stamp duty and other government charges are paid
- Agent releases keys to you or your representative
Most buyers don't attend settlement personally-your conveyancer handles all procedural requirements on your behalf. You'll typically receive confirmation of successful settlement by phone or email, followed by arrangements to collect your keys.
Avoiding Common Mistakes When Buying Homes
Even experienced property buyers occasionally make costly errors that affect their purchase outcome or long-term satisfaction. Learning from common mistakes helps you avoid these pitfalls and make informed decisions throughout the process.
Emotional Decision-Making Over Objective Analysis
Falling in love with a property before completing thorough due diligence creates vulnerability to poor decisions. While emotional connection to a potential home is natural, it shouldn't override objective assessment of value, condition, and suitability for your needs.
Maintain perspective by viewing multiple properties, taking detailed notes during inspections, and sleeping on major decisions before committing to offers. The comprehensive homebuying process guide emphasises systematic evaluation over emotional reactions.
Insufficient Research and Preparation
Rushing into property purchases without adequate market research, financial preparation, or professional guidance frequently leads to buyer's remorse. Understanding how to avoid regret when buying a home requires thorough preparation across all aspects of the purchasing journey.
Common research failures include:
- Inadequate suburb research beyond online property portals
- Failing to understand local market price trends and growth potential
- Overlooking future development that might affect property value
- Insufficient investigation of strata management quality for apartments
- Not visiting properties at different times to assess neighbourhood characteristics
Overlooking Hidden Costs and Ongoing Expenses
First-time buyers particularly underestimate the ongoing costs of homeownership beyond mortgage repayments. Council rates, water charges, insurance, maintenance, and potential strata fees quickly accumulate into significant annual expenses.
Budget realistically for these ongoing ownership costs when determining what you can genuinely afford. A comprehensive home buying checklist helps ensure you've considered all financial implications before committing to purchase.
First Home Buyer Considerations and Advantages
First-time buyers face unique challenges but also access specific benefits and support schemes designed to help Australians enter the property market. Understanding these advantages ensures you maximise available opportunities.
Government Grants and Stamp Duty Concessions
Various federal and state government initiatives support first-home buyers through grants, stamp duty concessions, and deposit guarantee schemes. These programs significantly reduce upfront costs and make homeownership more accessible.
Current first-home buyer support includes:
- First Home Owner Grant providing cash grants for eligible new home purchases
- Stamp duty concessions or exemptions reducing purchase costs by thousands of dollars
- First Home Guarantee Scheme allowing purchases with deposits as low as 5% without lenders mortgage insurance
- First Home Super Saver Scheme enabling voluntary superannuation contributions for deposit savings
Eligibility criteria vary between schemes and states, so research thoroughly and confirm your eligibility before relying on these benefits in your purchasing strategy.
Building Knowledge and Confidence
The learning curve for first-time buyers is steep, covering unfamiliar legal terminology, financial concepts, and procedural requirements. Taking time to educate yourself through reputable resources, workshops, and professional consultations builds confidence for decision-making.
Consider following a structured approach like the nine essential steps to buying a home that breaks the process into manageable phases. This systematic approach prevents overwhelm and ensures you address all critical elements before proceeding to the next stage.
Long-Term Considerations Beyond the Purchase
Successful property ownership extends well beyond settlement day. Thinking ahead about property management, potential improvements, and future resale value ensures your purchase delivers long-term satisfaction and financial returns.
Property Maintenance and Improvements
Regular maintenance protects your investment value and prevents minor issues escalating into major problems. Develop a maintenance schedule covering essential tasks like gutter cleaning, pest inspections, air conditioning servicing, and exterior repainting.
Strategic improvements can enhance both lifestyle enjoyment and property value. Prioritise renovations that deliver strong returns like kitchen updates, bathroom improvements, and outdoor entertaining areas. Avoid overcapitalising by improving beyond the suburb's typical price point.
Understanding Market Cycles and Future Value
Property markets move in cycles of growth, plateau, and occasional decline. While timing the market perfectly is impossible, understanding broader trends helps inform decisions about when to buy, hold, or eventually sell.
Factors influencing long-term property value include:
- Infrastructure development improving accessibility and amenity
- Population growth driving demand in the area
- Economic conditions affecting employment and income levels
- Interest rate trends influencing buyer borrowing capacity
- Supply constraints limiting new housing development
Properties in established suburbs with strong fundamentals like Padstow, Revesby, and Panania typically demonstrate resilience through market cycles due to consistent demand, quality infrastructure, and limited development opportunities.
Successfully buying homes requires careful planning, thorough research, and strategic decision-making across multiple stages from initial preparation through to settlement. Understanding your financial capacity, engaging professional support, conducting comprehensive due diligence, and maintaining emotional discipline throughout negotiations positions you to secure the right property at a fair price. Whether you're purchasing your first home or adding to an investment portfolio, working with experienced professionals who understand local markets makes the journey significantly smoother and more successful. Steven Cirillo provides expert guidance throughout the entire buying journey, helping clients understand the process, navigate inspections, review market opportunities, and make confident decisions backed by extensive local knowledge across Revesby, Padstow, Panania, and surrounding suburbs. Contact Steven Cirillo today to receive personalised support that helps you secure the right property at the right price with confidence and clarity.